US President Donald Trump on Wednesday slapped an additional 25 per cent tariff on goods coming from India as penalty for New Delhi's continued buying of Russian oil.
India celebrated Dhanteras, the biggest gold buying festival, followed by Diwali, when scarcity of the yellow metal and high prices pushed consumers to buy silver and diamond jewellery.
Gold, a safe-haven bet, is likely to continue its record-smashing journey in the New Year, rising to Rs 85,000 per 10 grams and even Rs 90,000 level in domestic markets if geopolitical tensions and global economic uncertainties continue.

The escalation of conflict in the West Asian region is expected to push already high logistics costs besides hurting trade in sectors such as oil, electronics and agriculture, according to exporters. They said that insurance costs for exports to the countries directly involved in the war could also go up, which will impact Indian exporters' working capital. Think tank Global Trade Research Initiative (GTRI) stated that the conflict is already hurting India's trade with countries like Israel, Jordan, and Lebanon.

India has imposed several restrictions on imports of gold, the biggest non-essential import item, to curb a record trade deficit.

The move came against the backdrop of Turkiye backing Pakistan and its condemnation of India's strikes on terror camps in the neighbouring country and Pakistan-occupied Kashmir under Operation Sindoor.
The 80:20 rule mandates importers to channel at least 20% of the import quantity for jewellery exports.

Govt has so far refused to bring down the import duty to 2% from the current 10%.

The government has asked jewellers to provide information on purchases of gold bars or jewellery worth more than Rs 500,000 by the end of this month, a move seen keeping a check on big transactions amid rising smuggling.
Precious ornaments are estimated to become 3% costlier under GST

The panel will look into issues related to compliance procedure.
Spot gold fell as far as $1,142.10 an ounce on Thursday, its lowest since November 2014.
Nearly two-thirds of India's gold demand comes from rural areas where jewellery is a traditional store of wealth for millions who have no access to the formal banking system.
Concern would kick in if imports stay at or over 100 tonnes a month.
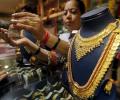
Jewellers sold huge quantities of precious ornaments at a premium of up to 50%.

Regaining the lost sheen, sales of gold jewellery and coins are set to touch pre-COVID levels in volume terms on the auspicious Dhanteras as easing pandemic concerns and pent up demand saw consumers flocking to stores to buy the precious metal. Increased footfall at stores and brisk sales online as well as relatively softer gold prices compared to record Rs 57,000 per 10 grams level in August spurred increased buying, especially light weight offerings, on Tuesday. Dhanteras is considered to be auspicious for buying precious metals and other valuable items.
The country's exports rose by 23.69 per cent to $34.06 billion in January on healthy performance by engineering, petroleum and gems and jewellery segments even as trade deficit widened to $17.94 billion during the month, according to provisional data of the commerce ministry. Imports in January grew by 23.74 per cent to $52.01 billion, the data, released on Tuesday, showed. Trade deficit widened to $17.94 billion during the month as against $14.49 billion in the same month last year.
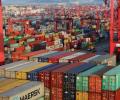
Exporters on Thursday sought a fund of Rs 750 crore for three years to tap USD 25 billion export potential in the US, aiming to seize potential opportunities that may arise as the US President-elect, Donald Trump, has threatened to impose high tariffs on Chinese goods. In its pre-Budget meeting with the finance ministry, Federation of Indian Export Organisations (FIEO) President Ashwani Kumar has also demanded extension of the five per cent Interest Equalisation Scheme (IES).
The new Companies Act that came in to force qualified the money mobilised by jewellery companies as deposits and as a result they had to discontinue such schemes.
After remaining in the positive zone for three months, India's exports contracted 1.2 per cent to $33.98 billion in July, while the trade deficit widened to $23.5 billion.
India's exports entered negative territory after a gap of about two years, declining sharply by 16.65 per cent to $29.78 billion in October, mainly due to global demand slowdown, even as trade deficit widened to $26.91 billion, according to data released by the commerce ministry on Tuesday. Key export sectors, including gems and jewellery, engineering, petroleum products, ready-made garments of all textiles, chemicals, pharma, marine products, and leather, recorded negative growth during October. Imports during the month under review rose by about 6 per cent to $56.69 billion on account of increase in the inbound shipments of crude oil and certain raw materials such as cotton, fertiliser and machinery.
India's merchandise exports dipped by about one per cent to $38.01 billion in December 2024 against $38.39 billion a year ago, according to government data released on Wednesday. Imports increased by 4.8 per cent to $59.95 billion in December 2024 compared to $57.15 billion in the year-ago month.
The heightened global uncertainty due to the US "reciprocal tariffs" on India may cause near-term corrections and market turbulence, but the long-term outlook remains constructive, market experts said on Thursday. The US has announced 27 per cent reciprocal tariffs on India, citing high import duties imposed by New Delhi on American goods.
Dealers are selling gold at a discount of Rs 175 for 10 gm.
Indian gold demand seen falling to 8-year low in festive quarter.
They would intensify the protest if their concerns are not addressed in the Budget.
Import in the first nine months of the current calendar year fell 20 per cent to 525 tonnes from 658 tonnes in the year-ago period.
India's exports rose by 2.14 per cent to $36.27 billion in July while the trade deficit almost tripled to $30 billion during the month due to over 70 per cent rise in crude oil imports, according to official data released on Friday. Imports shot up by 43.61 per cent to $66.27 billion in the month compared to July 2021, the data showed. The trade deficit was $10.63 billion in July 2021.

The best way to curb gold demand is by reducing black money in circulation.
After recording positive growth in September, India's exports declined 5.4 per cent to $24.82 billion in October on account of dip in shipments of petroleum products, gems and jewellery, leather, and engineering goods. Trade deficit in October narrowed to $8.78 billion as against $11.76 billion, as imports also fell 11.56 per cent to $33.6 billion during the month under review.
Gold bullion purchases across Asia slowed this week as a long rally in prices discouraged buyers.
Non-resident Indians are bringing gold into the country by taking advantage of rules that allow each individual to carry 1 kg of the metal, helping traders cope with restrictions on imports during the peak wedding season.

Imports in 2016 expected to be lowest in 7 years but experts don't rule out a revival in demand if the yellow metal's price falls

Jewellers see flat gold sales this Dhanteras

Supply through recycling of used gold declined to around 10 tonnes in the second quarter of the current calendar year.
India's exports in January rose 25.28 per cent to $34.50 billion on account of healthy performance by mainly engineering, petroleum and gems and jewellery sectors, even as trade deficit widened to 17.43 billion, according to data released by the commerce ministry on Tuesday. Imports grew by 23.54 per cent to $51.93 billion during the month under review. Trade deficit, difference between imports and exports, stood at $14.50 bn in January 2021.
By tying gold imports directly to export volumes, India is effectively trying to cap how much bullion can be brought into the country, tightening supplies and driving up local prices.
The government has not given any concrete assurance on the rollback of excise duty.

The jewellery industry has welcomed the government's decision to ban old Rs 500 and Rs 1,000 notes, saying gold demand will rise as people will have more faith in the precious metal than the currency notes. But the unorganised builders and secondary (resale) property market would be adversely impacted.
India's exports jumped 45.76 per cent to $33.28 billion in August on account of healthy growth in segments like engineering, petroleum products, gems and jewellery and chemicals, even as the trade deficit widened to a four-month high of $13.81 billion.
